INVESTMENT INSIGHTS
This assessment is based on company’s performance on Revenue growth, ROCE, Equity and Assets, key margin ratios, cash conversion cycle, and debt to cash flow from operations and how it compares with its long term averages.
Based on the industry it operates in, the relevant valuation ratios include one of the following, P/E, P/BV, P/Sales, EV/EBITDA or a combination of two or more.
| Valuation Ratios | Current | 5-year Historic Median |
|---|---|---|
| Price to Earnings | - | - |
| Price to Book | 1.28 | 0.63 |
| Price to Sales | 1.58 | 0.42 |
| EV to EBITDA | 336.07 | 4.87 |
We have analysed the performance of the company on the following:
By checking its Revenue growth, Gross, Operating and Net Margins compared to its last 5-year median.
By checking its ROCE, ROA, ROE and its Cash Conversion Cycle.
By checking its Debt to Equity and Cash Flow from Operations.
A: What are the trends in revenue and profit margins?
| Current Level | 5-year Historic Median |
|
|---|---|---|
| Gross Profit Margin (%) | -19.7 | -8.8 |
| Operating Profit Margin (%) | -26.14 | -5.38 |
| Net Profit Margin (%) | -20.87 | -14.88 |
B: Does the business utilize capital efficiently?
| Current Level | 5-year Historic Median |
|
|---|---|---|
| Asset Turnover (x) | 0.39 | 0.39 |
| ROE (%) | -9.01 | -8.72 |
| ROCE (%) | -8.06 | -1.52 |
| Cash Conversion Cycle | 323 days | -1653 days |
C: How much debt does the business have and is it at a sustainable level?
D: Promoter shareholding and pledge status of Datakosa Ltd?
E: How does Datakosa Ltd performance compare with that of its Peers?
| Current Level | 5-year Industry Median |
|
|---|---|---|
| Revenue Growth (%) | -63.4 | - |
| Gross Profit Growth (%) | 0 | 14.9 |
| Operating Profit Growth (%) | 0 | 17.1 |
| Net Profit Growth (%) | 0 | 16.1 |
| Current Level | 5-year Industry Median |
|
|---|---|---|
| Asset Turnover (x) | 0.39 | 0.5 |
| ROE (%) | -9.01 | 5.55 |
| ROCE (%) | -8.06 | 8.39 |
| Cash Conversion Cycle (days) | 322.78 | 36 |
| 9Y | 5Y | 3Y | 1Y | |
|---|---|---|---|---|
| Share Price CAGR |
-4.6% | -14.3% | 52.7% | -59.1% |
| Valuation Ratios | Current | 5-year Historic Median |
5-year Industry Median |
|---|---|---|---|
| Price to Earnings | - | - | 31.33 |
| Price to Book | 1.28 | 0.63 | 2.61 |
| Price to Sales | 1.58 | 0.42 | 4.42 |
| EV to EBITDA | 336.07 | 4.87 | 15.50 |
Start Research-backed Investing ...Now. Subscribe to Sapphire
MoneyWorks4Me is a SEBI-registered Investment Adviser (IA) dedicated to helping investors build long-term wealth through transparent, research-driven, conflict-free guidance. Founded in 2008, we started our journey as a Research Analyst (RA), providing deep fundamental analysis, intrinsic value insights, and long-term investing frameworks for Indian equities. In 2017, we transitioned to a full-fledged SEBI-registered Investment Adviser, strengthening our commitment to acting as a fiduciary—always putting the investor’s interest first.
To become India’s most trusted, research-powered fiduciary advisory platform—where every investor, regardless of experience, can make calm, confident, and well-reasoned investment decisions.
MoneyWorks4Me ensures this through:
MoneyWorks4Me rating and ranking of funds for SIP is available to subscribers only. Moneyworks4Me is not a rating and ranking agency, however it is required that users have a way of selecting funds and building a Portfolio. The method used by it are described below to enable users to understand the logic behind the rating and ranking Subscriber will find more details on this in the various content made available from time to time. In case you need more please write to besafe@moneyworks4Me.com
MoneyWorks4Me rates and ranks mutual funds based on the following data-driven system:
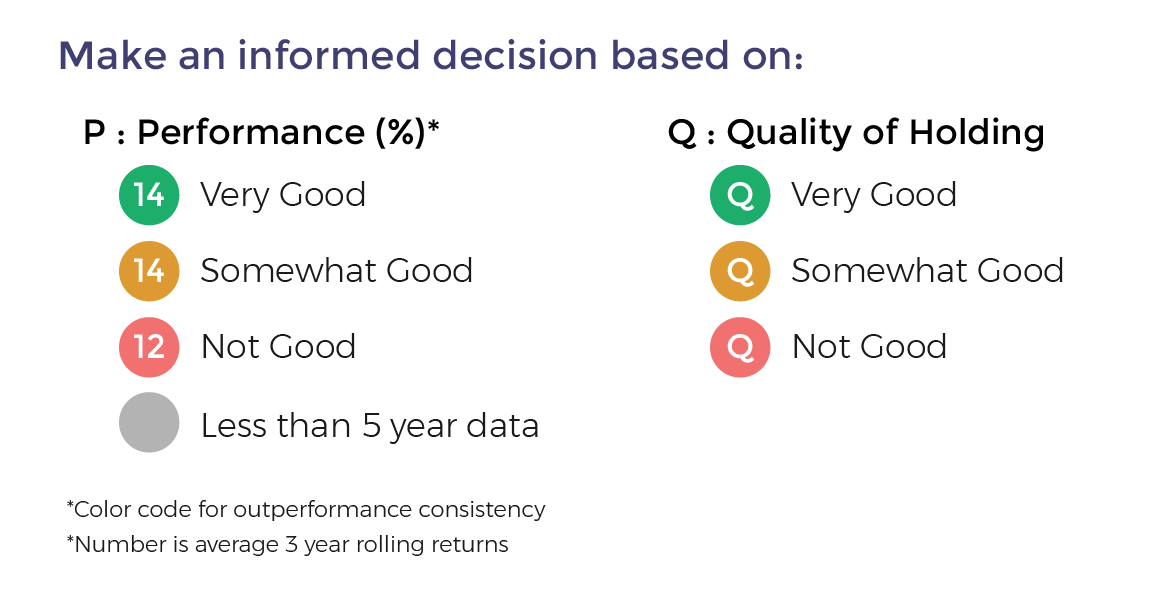
Funds ranking in screeners: Performance Consistency and Quality are two parameters used for ranking funds for SIP. The ranking as follows GG, GO, GR, OG, OO, OR, RG, RO and RR.
With the same color-coded funds, the one with the higher Average 3-year rolling returns (over 5 to 10 years), the number that appears in the Performance tag, ranks higher.
Here is the summary:
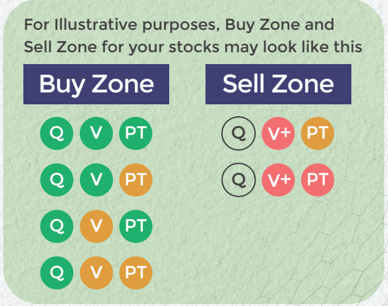
The third tag Upside Potential is not relevant for SIP. It is relevant for lumpsum investments in Mutual Funds.
Make an informed decision for Stocks
Invest using an intelligent system with powerful data-driven tools that help you identify opportunities and make informed buy-hold-sell decisions
Buy quality Stocks when they are available at reasonable prices and supported by an upward price trend and Sell when they are Overvalued using the Decizen Rating System. Covers 3500+ stocks

|
Name of the IA registered
with SEBI: |
The Alchemists Ark Pvt. Ltd. |
|
Logo:
|
|
|
Trade/Brand
Name of IA: |
MoneyWorks4Me Investment Advisers |
|
Brand Logo:
|
 |
|
SEBI Registration Number:
|
INA000013323 Validity – May 16, 2019 – Perpetual |
|
Registration:
|
Non-Individual |
|
BSE Enlistment No:
|
1187 |
|
Address:
|
B-101, Signet Corner Building, Balewadi Phata, Baner, Pune, Maharashtra 411045 |
|
Compliance Officer
Details: |
Name: Shrikant Jagtap Email: shrikant.jagtap@moneyworks4me.com |
Telephone: +919860359463 Address: Same as IA |
|
Grievance Officer
Details: |
Name: Mukta Vaze Email: mukta.vaze@moneyworks4me.com |
Telephone: +919860919463 Address: Same as IA |
|
Principal Officer
Details: |
Name: Atharva Bhide Email: atharva.bhide@moneyworks4me.com |
Telephone: +919175899463 Address: Same as IA |
|
Standard Warning:
|
Investment in securities market are subject to market risks. Read all the related documents carefully before investing. |
|
|
Disclaimer:
|
Registration granted by SEBI, enlistment with exchange and certification from NISM in no way guarantee performance of the intermediary or provide any assurance of returns to investors. |
|